Every claim you file goes into a national database called CLUE that insurers check before offering coverage or setting rates. A single claim typically increases your premium 20-40% for the next 3-5 years. Multiple claims can make you uninsurable in the standard market, forcing you into high-risk pools where premiums are 2-3x normal rates. The financial impact of filing a claim often exceeds the payout.
The math is straightforward but sobering. If you pay $1,800/year for insurance and file a $3,000 claim, your rates might jump to $2,500/year. Over five years, that's an extra $3,500 in premiums - more than the claim payout. You're essentially paying for your own claim through future premium increases while also risking policy cancellation. This is why the rule of thumb is to only file claims that exceed your deductible by at least 50%.
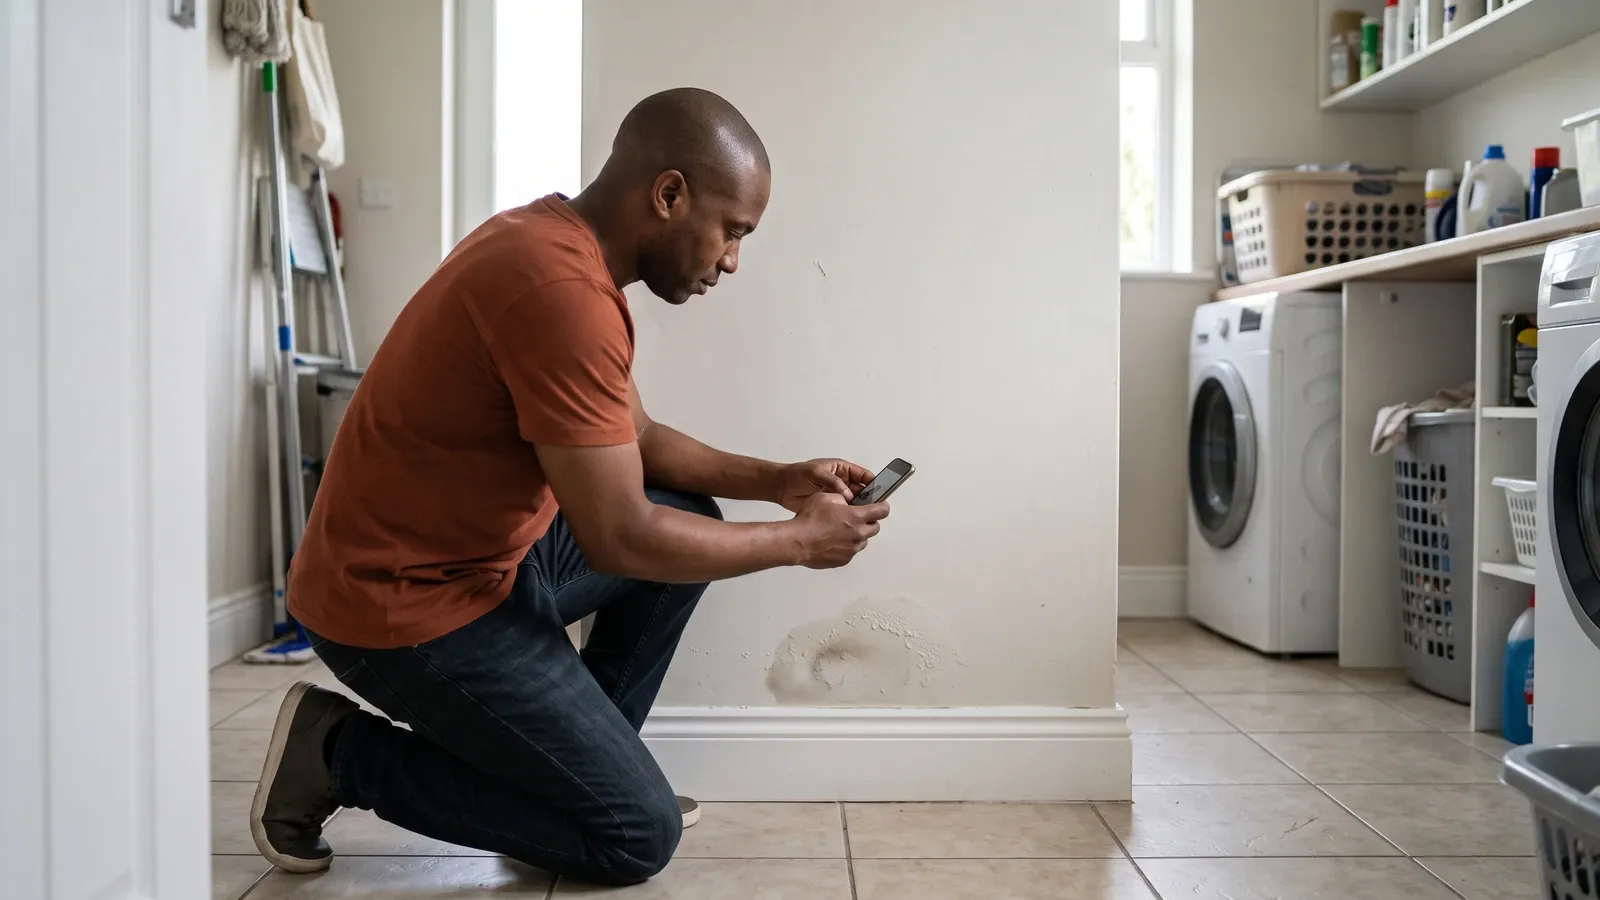
Water damage claims are particularly destructive to your insurability. Insurers view them as indicators of ongoing problems that will generate future claims. A single water damage claim can result in a 30% rate increase, and a second claim within five years often leads to policy cancellation. Many insurers now won't cover homes with two or more water claims in the past five years, regardless of the cause.
Strategic claim decisions protect your insurability. File for major catastrophic losses - fires, tornados, theft of expensive items - where the payout is substantial and the damage is beyond your ability to absorb. Pay out of pocket for smaller losses like minor roof damage, appliance leaks, or broken windows. Treat your insurance policy as protection against disasters, not a maintenance fund.
Higher deductibles can offset some of this risk. A $2,500 deductible instead of $500 typically saves 15-25% on premiums. This forces you to self-insure smaller losses while maintaining protection for major claims. The premium savings accumulate in your bank account instead of the insurance company's, effectively building your own emergency fund for minor home repairs.